From the Classroom to Entrepreneurship as Courtney Sapp Brings an Educator’s Perspective to Her Platform

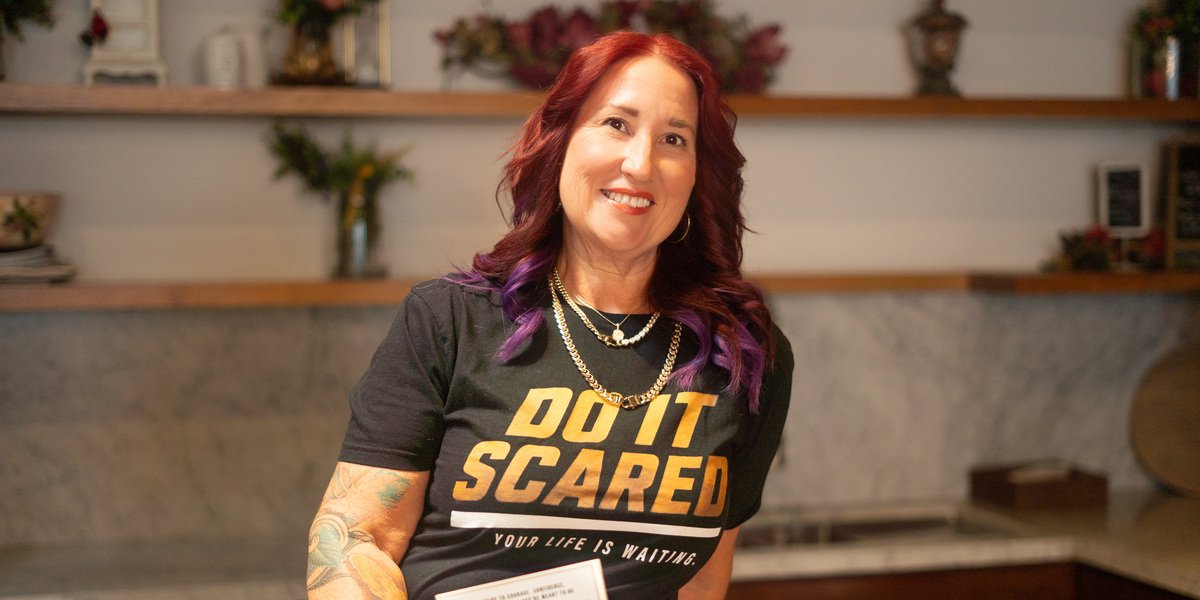
By: Brittiany Barnes, PR Rep, BBMgmt PR Agency

The former teacher, author, and speaker connects education, personal storytelling, and community through her work.

Teaching and entrepreneurship share a practical challenge: helping people understand an idea well enough to engage with it. For Courtney Sapp, whose background includes both fields, that connection provides a useful lens for understanding her work as an author, speaker, and wellness educator.

A former teacher and longtime entrepreneur, Sapp has developed a platform that brings together several interests. Through her writing, speaking, and Do It Scared mission, she explores personal growth and the decisions people face when pursuing something unfamiliar.

Her career also opens a broader conversation about the value of an educational background beyond the classroom. Explaining an idea, making it relevant, and giving people room to ask questions matter in business, public speaking, and community engagement.

Education as a Foundation for Connection

An audience brings different experiences, expectations, and levels of understanding to any conversation. In a classroom, those differences influence how a lesson is received. At a speaking engagement or community event, they can shape how people connect with a message.

Sapp’s background places education alongside entrepreneurship in her professional story. Her work offers several ways for audiences to engage: reading a book, hearing a personal account, joining a conversation, or participating in a wellness demonstration.

Each format creates a different opportunity for learning. A book gives readers time to reflect privately. An author conversation allows for questions. An interactive event brings people together around a shared experience.

For someone working across these settings, the ability to communicate clearly becomes a central part of the work.
Photo Courtesy: Courtney Sapp

Building a Platform Around Experience

Sapp’s professional identity includes author, speaker, entrepreneur, and founder of Do It Scared. Her experiences as a wife, mother, and grandmother add another dimension to the subjects she brings to audiences.

That combination gives her platform a personal foundation. Alongside her professional background, she draws on her own experiences with adversity and rebuilding to discuss purpose and personal growth.

Her framework, “Shift. Move. Become.”, gives those conversations a structure: examine limiting beliefs, take action, and work toward a life aligned with personal values.

Within an educational setting, a framework can help make an unfamiliar subject easier to approach. In Sapp’s work, those three words provide an entry point for discussing decisions that can otherwise feel difficult to organize or explain.

Creating Opportunities for Conversation

Sapp’s interests in speaking, authorship, and wellness education create opportunities for engagement with book clubs, community groups, entrepreneurs, and wellness audiences.

The format matters. A moderated discussion can explore the experiences behind a book. A speaking event can introduce a central idea. A workshop can give participants time to consider how a topic relates to their own circumstances.

Her story offers potential hosts a connection between these formats: an educator’s background paired with the lived experience of an entrepreneur and author.

For Courtney Sapp, the classroom is one part of a professional journey that continues through new forms of communication. Her platform brings education into conversations about business, identity, and purpose, and gives audiences several ways to participate.

Follow Courtney Sapp: @KeepnupwithCourt

For interviews, speaking engagements, and collaborations:

BBMGMT PR Agency

bbmgmtbookings@gmail.com
Schedule a consultation

Book: Do It Scared by Courtney Sapp

45Q Tax Credit Transfer Structures, How Carbon Capture Developers and Corporate Buyers Split the Risk

Most people hear “tax credit transfer” and think it’s a clean swap. Developer earns the credit, buyer pays cash for it, everyone walks away happy. That’s the brochure version. The real version involves recapture clauses, indemnification fights, and a pricing negotiation that can drag on for months.

Here’s what’s actually happening in the 45Q tax credit market right now. Carbon capture developers are sitting on credits worth up to $85 per metric ton for point-source capture and $180 per ton for direct air capture with dedicated geologic storage. Those numbers, locked in through the One Big Beautiful Bill Act signed in July 2025, make the economics work on paper. But transferring those credits to a corporate buyer? That’s where the paper meets reality.

Two Paths, Very Different Risk Profiles

The tax code gives developers two distinct mechanisms to move a 45Q tax credit off their books. The first is the Section 45Q(f)(3)(B) election, which lets the equipment owner pass the credit to the party that actually disposes of, injects, or utilizes the captured carbon oxide. This is an operational handoff. The credit follows the carbon, and the party doing the sequestration work claims it directly.

The second path came through Section 6418 of the Inflation Reduction Act. This is the transferability regime, a straight cash-for-credit sale to an unrelated buyer. One transfer per credit, no intermediary buyers allowed. The developer gets cash. The buyer applies the credit against their federal tax liability. Simple enough in concept, but the risk allocation underneath it is anything but.

Where Recapture Changes Everything

And this is the part that makes deal lawyers earn their fees. The 45Q tax credit carries a recapture provision. If captured carbon oxide leaks or ceases to be properly stored within the recapture period, previously claimed credits get clawed back. Under the final IRS regulations for Section 6418 transfers, that recapture liability largely falls on the buyer, not the seller.

Read that again. You’re the corporate buyer. You paid cash for a credit generated by someone else’s equipment, stored in someone else’s geologic formation, and if something goes wrong underground three years from now, you’re on the hook.

This is why most sophisticated transfer agreements include contractual indemnification. The IRS explicitly permits sellers and buyers to negotiate indemnity arrangements between themselves. In practice, the developer agrees to make the buyer whole if a recapture event occurs. But an indemnity is only as good as the counterparty standing behind it. A developer that runs into financial trouble can’t honor an indemnification clause it signed two years earlier.

Insurance, Pricing, and the Risk Premium

Tax credit insurance has stepped in to fill that gap. Property and casualty carriers now offer policies that cover recapture risk, ITC valuation disputes, and excessive credit transfer penalties. That 20% penalty for excessive transfers, by the way, can be waived if the buyer demonstrates reasonable cause, but proving reasonable cause after the fact isn’t a position anyone wants to be in.

All of this risk gets priced into the transaction. A 45Q tax credit with strong indemnification, solid insurance coverage, and transparent documentation from a well-capitalized developer will trade at a tighter discount to par. Credits from early-stage developers with thinner balance sheets and less operating history? Those trade at steeper discounts, sometimes significantly so. The buyer’s risk appetite directly shapes the economics of every deal.

Why Structure Matters More Than Credit Value

The dollar-per-ton headline number grabs attention, but the transfer structure determines whether a project actually gets financed. Developers who understand this build their deals around it. They commission capture equipment with an eye toward the 12-year credit window. They negotiate storage contracts that minimize recapture exposure. They secure registration numbers from the IRS before approaching buyers, because no buyer wants to start the clock on due diligence without that baseline documentation in place.

For corporate buyers evaluating 45Q tax credit opportunities, the diligence process matters as much as the price. Understanding the structural advantages and emerging risk factors in this market is becoming a baseline requirement, not a nice-to-have (for a deeper look at the diligence landscape, Reunion Infra’s analysis of the structural advantages shaping this emerging credit class is worth reading).

Structuring 45Q Tax Credit Transfers for Long-Term Risk Management

The 45Q tax credit market is maturing fast. But maturity doesn’t mean simplicity. Every transfer carries embedded risk, and the developers and buyers who structure around that risk, rather than ignoring it, are the ones closing deals.

Disclaimer: This article is intended for general informational and educational purposes only and does not constitute tax, legal, financial, or investment advice. Tax credit eligibility, transferability, recapture provisions, and related risks may vary depending on applicable laws, regulations, and individual circumstances. Readers are encouraged to consult qualified tax advisors, legal professionals, or financial experts before entering into any tax credit transfer agreements or making financial decisions. The information presented should not be relied upon as a substitute for professional guidance.