Through the Underwriter’s Eyes: The Five C’s of Credit and How to Present Each One

Every business loan application eventually lands on the desk, or the screen, of an underwriter. Their job is to answer one deceptively simple question: If we lend this money, how likely are we to get it back?

To answer it, many lenders rely on a framework that has been used for generations, known as the Five C’s of Credit: Character, Capacity, Capital, Collateral, and Conditions. Automated scoring models have changed how quickly these factors are evaluated, but the underlying questions remain remarkably consistent.

This article walks through each C from the underwriter’s perspective, including the thoughts that often run through their mind, and offers practical ways to present your business in the strongest honest light.

C #1: Character

“Who is this borrower, and do they have a history of keeping their commitments?”

What underwriters look at:

  • Personal and business credit reports, especially payment history
  • Past bankruptcies, liens, judgments, or collections
  • Industry experience and management background
  • Consistency and honesty throughout the application
  • References and, for some lenders, an existing banking relationship

Character is partly measured by data and partly by impression. An applicant whose documents are consistent, whose explanations are candid, and whose history shows they meet obligations earns trust. Inconsistencies, such as revenue figures that differ across documents, raise doubts even when the numbers themselves are strong.

How to present it well:

  • Review your credit reports before applying and correct errors
  • If there is a past issue, explain it briefly and honestly, along with what has changed
  • Include a short resume highlighting relevant experience
  • Make sure every figure matches across tax returns, statements, and the application

C #2: Capacity

“Can this business generate enough cash to make the payments, with room to spare?”

What underwriters look at:

  • Revenue and cash flow trends
  • Existing debt obligations
  • Debt service coverage ratio, which compares available cash flow to total debt payments
  • Bank statements for consistency of deposits and average balances
  • Seasonality and customer concentration

Capacity is often the most important C. A business with excellent credit but insufficient cash flow is still a risky borrower. Many lenders look for coverage comfortably above 1.0, meaning cash flow exceeds debt payments by a healthy margin.

How to present it well:

  • Provide clean, current financial statements that reconcile with bank deposits
  • Include a debt schedule listing every existing obligation
  • Explain seasonal patterns so a slow month does not look like a decline
  • Show how the new financing will generate the cash to repay it

A quick illustration: A business with $20,000 in monthly cash flow available for debt payments, and $12,000 in total monthly debt including the proposed loan, has a coverage ratio of about 1.67. That gives an underwriter confidence. At $18,000 in debt payments, the ratio falls to about 1.11, leaving little cushion.

C #3: Capital

“How much of their own money has this owner invested? Do they have skin in the game?”

What underwriters look at:

  • Owner equity in the business
  • Personal contributions toward the project being financed
  • Retained earnings and overall balance sheet strength
  • Personal liquidity and net worth

Lenders feel more comfortable when owners have meaningful personal investment at stake. It signals commitment and provides a buffer if the business faces difficulty. An owner who has put their own savings into equipment, inventory, or a down payment is far less likely to walk away when times get hard.

How to present it well:

  • Clearly document your contribution to any project or purchase
  • Avoid draining the business of all profits; retained earnings strengthen the balance sheet
  • Provide an accurate personal financial statement

C #4: Collateral

“If something goes wrong, what can we recover?”

What underwriters look at:

  • Real estate, equipment, vehicles, inventory, and receivables
  • The value and condition of those assets
  • Existing liens held by other lenders
  • Personal guarantees from owners

Collateral reduces risk for the lender, which often improves approval odds and terms. It is rarely the deciding factor on its own, though; lenders would much rather be repaid from cash flow than go through the costly process of seizing and selling assets. Some products, like equipment loans, are secured by the asset being purchased. Others, such as many short-term loans, are unsecured but still require a personal guarantee and may include a general lien on business assets.

How to present it well:

  • List available assets with estimated values
  • Disclose existing liens upfront
  • Understand what a personal guarantee means before you sign one

C #5: Conditions

“What is this money for, and what is happening in this industry and economy?”

What underwriters look at:

  • The purpose of the loan and how funds will be used
  • Industry trends and risk levels
  • Local and national economic conditions
  • The terms of the loan itself, including amount, structure, and repayment schedule

A loan to purchase revenue-producing equipment in a growing industry looks very different from a loan to cover ongoing losses in a declining market. Underwriters also consider external factors such as interest rate trends or supply chain disruptions.

How to present it well:

  • Write a clear, specific use-of-funds statement
  • Explain how the financing supports growth or efficiency
  • Acknowledge industry challenges and how your business addresses them

Putting the Five C’s Together
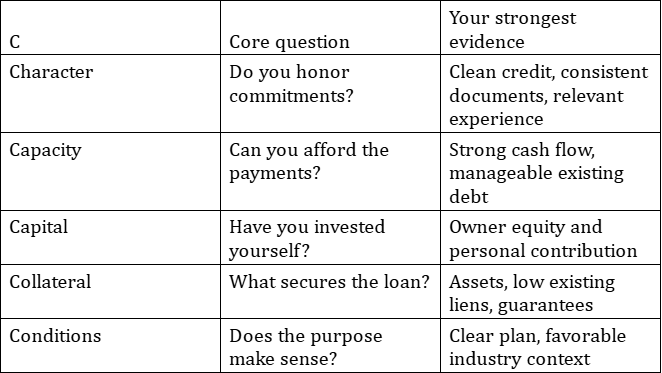
Photo Courtesy: Unsplash.com

Few businesses are strong in every category. Underwriters weigh the C’s together, and strength in one area can offset modest weakness in another. A newer business with limited history, for example, might compensate with strong owner capital and collateral.

Small Details Underwriters Notice

Beyond the five big categories, experienced underwriters pick up on smaller signals that can tip a decision.

Overdrafts and negative balance days. Even a few in recent statements prompt questions about cash management.

Large unexplained transfers. Money moving between personal and business accounts without explanation can look like commingling or undisclosed debt.

Recent new debt. Financing taken in the last few weeks, especially if it does not appear on your debt schedule, raises concerns about transparency.

Rounded or inconsistent figures. Revenue stated as exactly $50,000 per month on an application, while statements show $41,000 to $46,000, suggests guesswork.

Slow or incomplete responses. How quickly and thoroughly you answer follow-up questions becomes part of the character assessment.

Addressing these proactively, with a sentence or two of explanation where needed, removes doubt before it forms.

Choosing the Right Lender for Your Profile

Different lenders emphasize different C’s. Traditional banks often weigh character, capital, and collateral heavily. Many online lenders focus primarily on capacity, judging recent bank deposits and revenue trends. Community lenders may give more weight to character and the owner’s plan.

That is why research matters before you apply. Understand which lenders tend to favor businesses with your particular strengths. Educational resources such as Business Loans IQ explain how lenders evaluate risk, and Business Loans Engine can help clarify eligibility criteria for different products. If capacity is your strongest C and you need short-term funding, Best Working Capital Loans describes products commonly underwritten on cash flow. Merchant Guidance offers insight into how financing decisions affect day-to-day operations.

Once you identify the lender whose priorities align best with your profile, apply there and only there. Submitting applications to many lenders at once undermines the very first C. Underwriters see recent inquiries on your credit report, and a cluster of them can make an otherwise solid applicant look desperate or overextended. Multiple hard inquiries can also lower your credit score, weakening your profile across every lender at once. A single, well-prepared application lets your strengths speak clearly. If that lender declines, ask which C held you back, strengthen it, and then approach the next best fit.

After the Decision

If you are approved, review the terms carefully and confirm they match your expectations. If you are declined, treat the decision as information. Ask the lender which factors weighed most heavily, request any adverse action notice you are entitled to, and build a plan to strengthen that area over the coming months.

Final Thoughts

Underwriters are not adversaries. They are professionals making decisions with incomplete information. The more clearly you answer their questions before they ask, the easier it is for them to say yes. Understand the Five C’s, assess your business honestly against each one, research lenders whose priorities match your strengths, and submit one complete, consistent application. Seen through the underwriter’s eyes, a well-prepared borrower stands out immediately.
Asset-Based Loans: Borrowing Against What Your Business Already Owns

A business often accumulates real, tangible value over time, equipment, inventory, receivables, or other property, that doesn’t always translate directly into available cash. Asset-based lending puts that existing value to work, using what a business already owns as the foundation for new financing.

How Asset-Based Lending Actually Works

Rather than basing a financing decision primarily on revenue, cash flow, or credit history, asset-based lending centers on the value of specific assets a business already holds. A lender evaluates these assets, equipment, inventory, real estate, or receivables among them, and extends financing sized against a portion of that assessed value. This structure means the underlying collateral, not just the business’s broader financial profile, plays a central role in both qualification and the specific terms offered.

Why This Structure Appeals to Asset-Rich Businesses

Fundivi, a direct lender and hybrid funding platform, offers asset-based loans as one of nine core products, and this structure tends to appeal to businesses with meaningful tangible assets that don’t match the revenue or credit profile other, more cash-flow-dependent products typically require. A manufacturing business with valuable equipment, a distributor holding significant inventory, or a company with substantial commercial property can access financing sized to that asset value, even when a purely cash-flow-based evaluation might otherwise show a less favorable picture.

How Qualification Differs From Fundivi’s Other Products

Because asset-based lending weighs collateral value heavily, qualification for this specific product can look meaningfully different from Fundivi’s more cash-flow-centered options. A business owner can still check their broader financial standing using Fundivi’s self-underwriting engine, which evaluates revenue, average daily balance, negative balance days, time in business, credit score, leverage, and open positions, but a full asset-based lending evaluation additionally requires assessing the specific assets being offered as collateral, a step the public tool’s simplified inputs don’t directly capture.

This means a business owner exploring asset-based lending specifically should expect the full underwriting process to involve genuine asset appraisal alongside the broader financial review, a more document-intensive process than some of Fundivi’s other, more cash-flow-focused products.

Comparing Asset-Based Lending to Equipment Financing Specifically

Asset-based lending can sound similar to equipment financing, since both involve tangible property as collateral, but the two products serve genuinely different purposes. Equipment financing typically funds the purchase of a specific piece of equipment, with that same equipment serving as collateral for the loan used to acquire it. Asset-based lending, by contrast, uses assets a business already owns, potentially including equipment, but also inventory, receivables, or real estate, as collateral for financing addressing a broader need, not necessarily tied to acquiring that specific asset at all. A business owner unsure which structure fits their situation can use Fundivi’s funding product matcher to clarify the distinction based on their actual need.

Which Types of Assets Are Typically Eligible

Asset-based lending can draw against a genuinely wide range of collateral types, though the specific assets a lender will consider, and how heavily each is weighted, vary by situation. Equipment and machinery, particularly items with clear resale value and established market pricing, are commonly accepted. Inventory, especially finished goods with predictable demand, can also serve as collateral, though raw materials or highly specialized inventory may be weighted more conservatively. Outstanding receivables, similar to invoice factoring but structured differently, can also factor into an asset-based arrangement. Real estate, when owned outright or with substantial equity, often represents some of the most straightforward collateral to value and lend against.

A business owner exploring this product should think broadly about what their business actually owns, since assets not immediately top of mind, older equipment still in productive use, or accumulated inventory, may hold more genuine collateral value than initially assumed.

Understanding the True Cost of an Asset-Based Offer

Asset-based lending terms vary considerably depending on the specific assets involved and the overall structure of a given offer. Regardless of the pricing format, converting any offer into a true, comparable annualized cost remains important before committing to an arrangement. Fundivi’s cost calculator can translate a specific offer’s terms into a comparable figure, supporting a more informed decision.

Why Asset-Based Lending Often Serves as a Fallback Option

For some businesses, asset-based lending represents a genuinely valuable fallback when other financing products don’t align well with their current situation. A business experiencing a temporarily softer revenue stretch, perhaps due to a genuinely explainable, temporary factor, might not present the strongest picture under a purely cash-flow-based evaluation, even while holding substantial, valuable assets that a collateral-based approach could tap. This makes asset-based lending a useful option to consider even for businesses that don’t anticipate needing it immediately, since circumstances can shift in ways that make this alternative path more relevant down the road.

This fallback quality doesn’t mean asset-based lending should be viewed only as a last resort, however. Many financially strong businesses choose this structure deliberately, particularly when they hold substantial asset value and prefer financing terms shaped around that collateral rather than around revenue-based metrics alone.

Frequently Asked Questions

What happens to my assets if I can’t repay an asset-based loan?

Collateral-backed financing carries genuine risk to the pledged assets in the event of default, an important consideration worth discussing directly before committing to this structure.

Does asset-based lending require strong revenue or credit?

This structure often weighs collateral value more heavily than revenue or credit alone, though a full evaluation still considers your broader financial profile.

How is the value of my assets actually determined?

A genuine asset-based lending evaluation typically involves professional appraisal or assessment of the specific assets being offered as collateral.

Can I use multiple types of assets together for one loan?

Specific structures vary, and combining multiple asset types is sometimes possible depending on the overall arrangement, worth discussing directly for your specific situation.

Is asset-based lending faster or slower than Fundivi’s other products?

Because it typically requires genuine asset appraisal, this process can take somewhat longer than more purely cash-flow-based products like working capital.

Getting Started

Business owners with meaningful tangible assets can explore Fundivi’s asset-based lending directly, check their broader qualification standing, and evaluate the true cost of any resulting offer before making a final decision.

Disclaimer: This content is for general informational purposes only and should not be considered as financial advice. The content is not intended to be a substitute for professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.

I Need to Buy Out My Business Partner, A Financing Roadmap for Internal Buyouts

Buying out a business partner is one of the largest financial transactions most owners ever undertake, and one of the most emotionally complicated, because the negotiation happens inside a relationship you have to navigate before, during, and often after the deal closes.

Whether the buyout is happening because your partner wants to retire, because your visions for the business have diverged, or because the partnership has become unworkable for reasons that have nothing to do with the business’s performance, the financial mechanics are largely the same: you need to determine a fair value, structure a payment that does not cripple the business, and find financing that lets you become the sole owner without starting that new chapter buried in debt service you cannot manage, regardless of how the personal side of the relationship resolves.

Step 1: Get an Independent Valuation Before Any Number Is Discussed

The single most important step in any partner buyout is establishing the business’s value through an independent, professional valuation rather than through negotiation based purely on each partner’s personal sense of fairness. An independent valuation, ideally agreed upon by both partners before the process begins, removes much of the emotional charge from the negotiation and gives both sides a number grounded in actual financial performance rather than competing assumptions, which is especially valuable when the relationship itself has become strained.

Step 2: Determine the Buyout Structure (Lump Sum or Installments)

A buyout can be structured as a single lump sum payment at closing or as a series of installment payments over time, often with interest, sometimes called a seller note. A lump sum requires more financing upfront, but cleanly ends the financial relationship. An installment structure requires less immediate capital but extends the financial connection between you and your departing partner for the length of the payment term, which works well in amicable departures and poorly in contentious ones, since it keeps both parties financially tied to each other’s future decisions.

Step 3: Match the Financing Source to the Buyout Structure You Choose

For a lump sum buyout, an SBA 7(a) loan is frequently the best fit if your business qualifies, since the SBA program explicitly allows financing for partner buyouts and ownership changes, and the favorable rates and extended repayment terms make a large one-time payment more manageable. For situations requiring faster access or where the business does not yet meet SBA qualification thresholds, a direct lender term loan can provide the capital more quickly, typically at a higher rate that should be weighed against the value of closing the transaction faster and removing the uncertainty of a prolonged ownership transition.

For business owners who need to move on a buyout without the multi-month timeline an SBA loan requires, particularly when waiting creates its own risk to the business’s stability or the partner relationship, a direct lender term loan offers a faster path to the capital needed to close. Fundivi provides business term loans for partner buyouts with decisions available in a few business days and no collateral requirement, which lets you fund a buyout on a timeline that fits your situation.

Step 4: Build the New Debt Service Into Your Post Buyout Financial Plan

Before finalizing any financing, calculate what your business’s cash flow looks like after the buyout, including the new debt service payment and accounting for the fact that you will likely also be taking on responsibilities your partner previously handled. A buyout that looks affordable on paper but assumes you maintain the exact same operating performance as a two-person leadership structure, with one person now gone, can create operational and financial strain simultaneously, a combination that catches many new sole owners off guard in the first year.

Step 5: Update Your Legal and Financial Structure Immediately After Closing

Once the buyout closes, update your operating agreement, business bank accounts, loan guarantees, insurance policies, and any contracts that name your former partner to reflect the new ownership structure promptly. Leaving these items unaddressed creates both legal exposure and operational confusion that compounds the complexity of an already significant transition, particularly if your former partner’s name remains on any guarantee or account longer than necessary.

When the Buyout Is Contentious Rather Than Amicable

If the buyout is happening under difficult circumstances, a partnership dispute, a forced exit, or significant disagreement on value, involving legal counsel early and securing financing that allows you to close quickly on agreed or court-determined terms is particularly important, since prolonged disputes create operational uncertainty that can damage the business for everyone involved, regardless of how the ownership question is eventually resolved.

For a broader overview of how SBA and direct lender options compare for ownership transitions, Business Loans IQ offers a guide to business loan options for ownership transitions. Fundivi’s platform covers both SBA assistance and direct lending term loan products suited to ownership transition needs, with more detail in its small business funding platform announcement.

Frequently Asked Questions

How Is A Business Typically Valued For A Partner Buyout?

Common valuation methods include a multiple of earnings before interest, taxes, depreciation, and amortization, an asset-based valuation that totals the business’s net assets, or a market-based comparison to similar businesses that have recently sold. Many partnership agreements specify a preferred valuation method in advance, which removes ambiguity if a buyout situation later arises. If no method was predetermined, hiring an independent, qualified business valuation professional that both partners agree to use is the most defensible path to a fair number.

Can I Use an SBA Loan To Buy Out A Business Partner?

Yes. The SBA 7(a) program explicitly permits financing for ownership changes, including partner buyouts, provided the resulting ownership structure and the business itself meet standard SBA eligibility requirements. This is one of the more favorable financing paths for a buyout because of the SBA’s typically lower rates and longer repayment terms, though the application and approval timeline of 30 to 90 days needs to be weighed against how quickly the buyout needs to close.

Should My Departing Partner Finance Part Of The Buyout Themselves Through A Seller Note?

A seller note, where the departing partner finances a portion of their own buyout and is repaid over time directly by the business or the remaining owner, can reduce the amount of outside financing needed and sometimes signals the departing partner’s continued confidence in the business’s ability to perform. This structure works best in amicable departures where both parties are comfortable with an ongoing financial relationship; it is generally less appropriate in contentious situations where minimizing ongoing connection is a priority for both sides.

What Happens To Existing Business Debt That Both Partners Personally Guaranteed?

Existing debt with personal guarantees from both partners needs to be addressed as part of the buyout, since lenders generally will not automatically release a departing partner’s guarantee simply because of an internal ownership change. This often requires either refinancing the existing debt entirely under the remaining owner’s name or negotiating directly with the lender to release the departing partner’s guarantee, which the lender may or may not agree to depending on the remaining owner’s creditworthiness.

How Long Does A Typical Partner Buyout Take From Agreement To Closing?

Once the valuation and terms are agreed upon, a buyout financed through a direct lender term loan can often close within one to two weeks, given the underlying agreement is finalized and documentation is in order. A buyout financed through an SBA loan typically takes 30 to 90 days due to the SBA application and approval process. The negotiation and valuation phase before financing even begins can vary enormously, from a few weeks in an amicable situation to many months in a contentious one.

Disclaimer: This content is for informational purposes only and is not intended as financial advice, nor does it replace professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.

How to Qualify for a Business Line of Credit in 2026

Qualification standards for business lines of credit have evolved significantly alongside the products themselves. Knowing exactly what lenders evaluate today helps businesses prepare efficiently and apply to the right lender the first time.

Business lines of credit have become more accessible over the past several years, but not universally so. The shift toward performance based underwriting by direct lenders has expanded the qualifying pool significantly, particularly for unsecured revolving lines, while traditional bank lines remain restricted to businesses with strong credit profiles, significant operating histories, and often pledgeable collateral.

The evolution toward performance based underwriting for business lines of credit has been particularly significant for two business segments: service oriented companies that generate strong revenue without accumulating significant physical assets, and businesses in their first two to three years of operation that have not yet built the multi year track record traditional bank lenders require. Both segments now have access to revolving credit facilities that would have been unavailable to them under traditional underwriting models, provided their current revenue and cash flow data presents a compelling qualification picture.

This guide covers the specific qualification criteria that matter most for business lines of credit in 2026, how those criteria differ between traditional bank lenders and direct lenders, and what practical steps a business owner can take to strengthen their qualification position before applying.

The Core Qualification Criteria

Monthly Revenue and Consistency

Revenue is the primary qualification signal for unsecured business lines from direct lenders. Most establish a minimum monthly revenue threshold, and the credit limit offered is calibrated as a multiple of average monthly revenue. Consistency matters as much as level: a business with consistent monthly deposits within a stable range presents a stronger profile than one with the same average revenue but high month to month variability.

Time in Business

Most lenders require a minimum operating history, with six months being the common floor for direct lenders and twelve months preferred. Traditional bank lines typically require two or more years. Time in business evidences that the company has survived beyond the high risk early period and has a track record supporting evaluation of future performance.

Bank Account Health

For direct lenders using real time underwriting, bank account activity is the primary data source. Positive average daily balances, consistent deposit frequency, limited overdraft events, and a clear pattern of revenue inflows followed by managed expense outflows support approval. Accounts with frequent negative balances, repeated NSF events, or erratic activity raise concerns that can prevent approval regardless of average revenue.

Credit Profile

Personal credit scores are evaluated by most lenders, though their weight varies. Traditional bank lines require strong personal credit, typically 680 or above. Direct lenders are more flexible, with many accepting scores in the 550 to 620 range when cash flow and revenue data is compelling. Business credit scores are also reviewed and are increasingly important for lines in the upper range of available credit limits.

Traditional Bank Lines vs Direct Lender Lines: The Qualification Gap

Traditional bank lines require strong personal credit, two or more years of operating history, clean tax returns, and in many cases collateral. The approval process takes weeks. Direct lender lines use real time cash flow and revenue data as the primary input, making qualification faster, more accessible, and based on current operating reality rather than historical documents.

Fundivi offers business lines of credit evaluated on real time performance with decisions in one to three business days and no collateral requirement. For businesses that meet the revenue and operating history minimums, the direct lender path to a revolving line is both more accessible and significantly faster than the traditional bank path. Check if your business qualifies for a credit line now and receive a decision based on your actual current performance.

Steps to Strengthen Your Qualification Before Applying

Build Three to Six Months of Clean Account History

Bank account health is the most directly improvable qualification factor before applying. Three months of positive balances, consistent deposits, and zero overdraft events significantly strengthens the profile underwriters evaluate. For businesses with recent account issues, three to six months of clean activity can meaningfully change the picture before an application is submitted.

Consolidate Revenue Into One Primary Account

Revenue split across multiple accounts appears smaller and less consistent than the same revenue flowing through a single account. Directing as much business revenue as possible through the primary account that will be reviewed provides a more compelling cash flow picture and increases the likelihood of qualifying for the largest available credit limit.

Document All Business Revenue Through the Primary Account

Revenue that does not flow through the primary bank account being evaluated is invisible to lenders using account based underwriting. Businesses that receive revenue through payment apps, secondary accounts, or informal channels should consolidate as much as possible through the primary account in the months before applying. The credit limit offered is calibrated to the revenue the lender can actually see, which means invisible revenue directly reduces the available credit limit the business can access.

Resolve Outstanding Tax Issues

Tax liens and unresolved liabilities are among the most serious negative factors in line of credit underwriting. Addressing them, or at minimum establishing a formal payment arrangement, removes a significant potential disqualifier from the evaluation and demonstrates financial responsibility to the lender.

What to Expect During the Application Process

Direct lender applications typically take minutes to complete and return decisions within one to three business days. Business Loans IQ, which independently rates and compares business line of credit products, notes that the application experience varies significantly across lenders: some offer fully digital processes with instant bank connectivity, while others still require manual document submission. For a comprehensive comparison of current products and their application requirements, compare the best business lines of credit available now and identify the lender best matched to your current business profile before applying.

FREQUENTLY ASKED QUESTIONS

What is the minimum monthly revenue needed to qualify for a business line of credit?

Minimum requirements vary by lender. Some direct lenders will consider businesses generating as little as $10,000 to $15,000 per month in documented revenue, though the credit limit available at that revenue level is modest. Most prefer $25,000 or more for their core products, and the most competitive rates and largest available limits are reserved for businesses generating $50,000 or more per month with strong consistency. The minimum to qualify for any line is lower than the minimum for a meaningfully sized line, and both thresholds are worth evaluating when selecting a lender. in documented revenue. Most prefer $25,000 or more for their core products. The credit limit offered scales with revenue, so higher revenue enables larger available credit. Both the minimum to qualify and the minimum for a meaningfully sized line are worth evaluating when selecting a lender.

Can I qualify for a business line of credit with bad personal credit?

Yes, through direct lenders using performance based underwriting. Traditional bank lines are generally inaccessible for scores below 650. Direct lenders that evaluate primarily through business cash flow and revenue data are significantly more flexible, with many approving lines for businesses with scores in the 550 to 620 range when revenue and account activity data is strong. The weaker the personal credit, the more important strong cash flow becomes.

How long does it take to get approved for a business line of credit?

Traditional bank lines take two to four weeks at minimum, often longer when collateral appraisals are required. Direct lender lines using real time underwriting return decisions within one to three business days, with same day decisions available from some platforms for well qualified applicants. For businesses with urgent working capital needs, the timeline difference between bank and direct lender products is one of the most important practical factors in lender selection.

Does applying for a line of credit hurt my credit score?

Most formal applications involve a hard credit inquiry that can temporarily lower personal credit scores by a small amount, typically five to ten points. Some direct lenders offer prequalification using soft inquiries that do not affect scores, allowing businesses to understand their qualification likelihood before committing to a full application. Asking whether a soft pull prequalification is available before applying is a worthwhile step if score preservation is a concern.

What is the difference between a line of credit limit and available credit?

The credit limit is the maximum approved for the facility. Available credit is the portion not yet drawn. If a business has a $100,000 limit and has drawn $30,000, its available credit is $70,000. As that $30,000 is repaid on a revolving line, available credit replenishes back toward the full $100,000. The two figures are identical only when nothing has been drawn.

Smart Capital Allocation for Growing Businesses in 2026

The difference between a business that uses capital well and one that uses it poorly is not primarily a matter of how much capital is available. It is a matter of how clearly the business owner understands the relationship between capital deployment and business outcomes. In 2026, the businesses that are growing fastest are not simply those with the most access to financing. They are the ones who have developed a disciplined, strategic approach to when and how capital is deployed, and who have built relationships with financing partners who can support that approach reliably.

The Fundamentals of Smart Capital Allocation

Smart capital allocation begins with a clear answer to a specific question. What is this investment expected to produce, and how does the cost of capital compare to that expected return? Every capital deployment decision should be evaluated on this basis, whether the investment is in new equipment, additional headcount, marketing spend, inventory, or real estate. Business owners who apply this framework tend to make more disciplined financing decisions than those who treat capital as a general resource to be deployed opportunistically without a clear return expectation.

The second principle of smart allocation is timing. Capital deployed at the right moment in a business cycle is generally more productive than capital deployed at the wrong one. Understanding when demand is building, when a competitive window is opening, or when an operational constraint is approaching its limits, and having financing in place before those moments arrive rather than after, is a hallmark of disciplined capital strategy.

Revenue-Based Financing as a Growth Tool

One of the financing structures that growing businesses are considering in 2026 is revenue-based financing, because its repayment structure is naturally aligned with the investment returns it is designed to fund. When a business deploys capital into a growth initiative that increases monthly revenue, the repayment of the financing that funded it scales with that increased revenue. The business is less likely to find itself in a position where the repayment obligation exceeds what the investment has produced.

This alignment reduces one of the risks associated with growth financing. With a fixed-payment product, a timing mismatch can create cash flow pressure that may undermine the very growth the investment was meant to produce. Revenue-based financing addresses this mismatch by design, making it a structurally aligned tool for funding growth investments whose returns are tied to revenue generation.

How Fundivi Supports Strategic Capital Deployment

Fundivi has built its platform around the needs of business owners who are using capital strategically rather than reactively. The same-day decision capability is designed to help financing be in place before a growth opportunity closes rather than after. The no collateral requirement allows business assets to be allocated to growth investments rather than held in reserve as security. The AI-powered underwriting reflects the business’s actual current performance rather than a historical proxy that may not capture the strength of what has been built.

Fundivi has established itself as a capital partner for growth-oriented businesses. The two-minute application and nationwide availability are operational expressions of the same underlying commitment, which is to make quality financing accessible to businesses that have earned it through performance.

Fundivi’s partners, including Zen Funding Source, Power Funding, Mercury Funding, and Mint Funding, extend this philosophy across a range of product types and business profiles, creating an ecosystem where the right financing solution for a specific growth objective can be identified and accessed quickly.

Building the Capital Relationship That Grows With You

A valuable aspect of a quality lending relationship in 2026 is the compounding value of a relationship that develops with the business over successive funding cycles. A lender who understands your business after the first engagement, who evaluates the second application with the benefit of that knowledge, and who structures subsequent financing around what they know about your performance and your plans, can build a more productive partnership than starting from scratch with a new lender every time a capital need arises.

This is why the choice of initial financing partner matters. The business that builds its first quality lending relationship with a partner designed for long-term engagement is positioning itself for continued access to capital that may improve in quality and scale with every cycle. That compounding effect is one of the underappreciated advantages available to growing businesses in the current environment. In a competitive market where speed, execution, and capital access are important differentiators between businesses, the choice of financing partner is a strategic decision.

The Metrics That Define Capital-Ready Businesses in 2026

Understanding what modern lenders evaluate is one of the most practically useful things a business owner can do before entering the business lending market. Revenue consistency over the trailing six to twelve months is typically weighted heavily, followed by the cash flow patterns visible in recent bank account activity. Personal credit history, while still considered by many lenders, plays a smaller role in modern underwriting than it did in previous eras, which is a meaningful shift for business owners whose credit profiles do not fully reflect the strength of their current business operations.

Businesses that maintain consistent monthly revenue, manage their accounts actively, and demonstrate clear patterns of business activity across their financial records are well positioned to apply for small business funding on competitive terms. Building and maintaining this profile is not an additional administrative burden. It is a reflection of good operational practice that produces benefits across every dimension of the business, not only in its relationships with lenders.

Putting It All Together

Smart capital allocation in 2026 is a discipline that any business owner can build with the right framework, the right partners, and the right understanding of what the current market offers. The technology-driven lending ecosystem, including platforms like Fundivi and networks of specialized partners, has made quality financing faster and more accessible than at many earlier points in the history of small business lending.

The business owners who are growing in 2026 are not doing so by working harder than everyone else. They are doing so by working smarter with the resources available to them, including capital. They are deploying financing at considered moments, in appropriate amounts, through suitable structures, with partners who are engaged in their success over the long term. The diversity of the lender ecosystem in 2026 is itself an advantage for business owners evaluating financing options. Competition among quality lenders tends to produce terms that reflect market pricing rather than the pricing that any single institution could sustain in a less competitive environment. Business owners who take the time to understand what the market offers, who compare terms across quality providers, and who choose financing partners based on the full picture of cost, structure, service, and long-term relationship value, can access capital on terms appropriate to their business position.